Sudden burst pipe — usually covered. Slow leak for six months — usually not. How water damage coverage actually works, and how to give your claim its best start.
The rule that decides most claims
Homeowners insurance is built around one distinction: sudden and accidental versus gradual and neglected. A pipe that bursts tonight, a water heater that ruptures, a supply line that pops off the washing machine — these are the classic covered losses. A leak that dripped behind a wall for six months, aging plumbing that finally corroded through, or damage from a roof worn out over years — carriers generally call those maintenance, and maintenance is the homeowner's side of the ledger.
Flood is its own category: rising water from outside — creeks, storm surge, surface water — is excluded from standard homeowners policies and requires separate flood insurance. And a sewer backup usually needs a specific endorsement, though many Maryland homeowners have one without realizing it. Your declarations page tells the story.
What to do in the first 24 hours
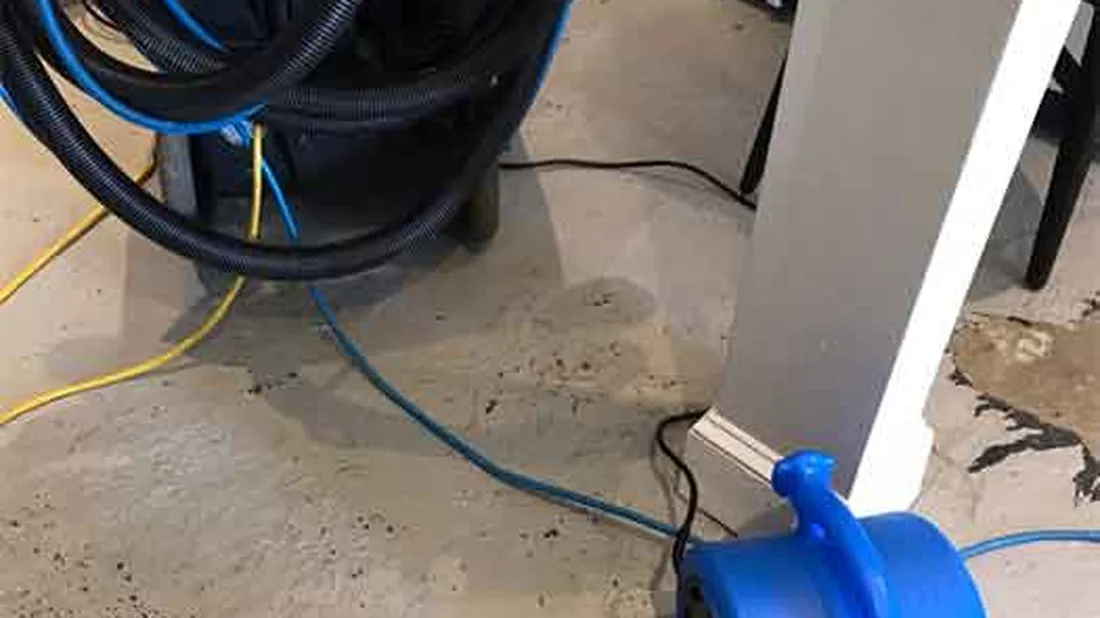
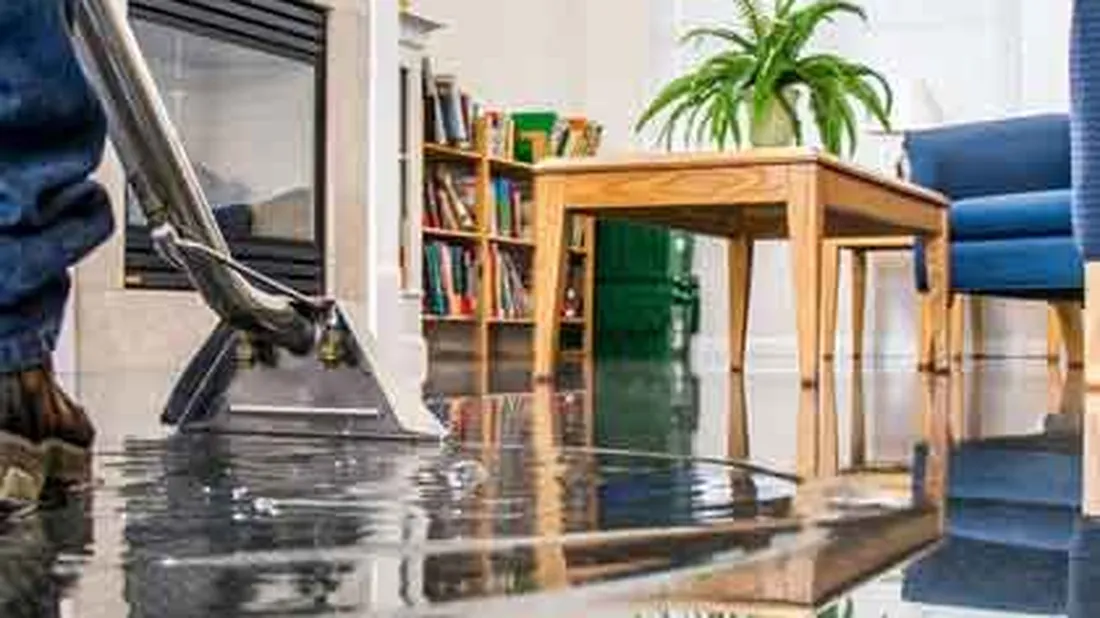
Stop the water if you safely can, then document before you disturb: photos and video of the source, the standing water and every affected room. Carriers cover the emergency mitigation — extraction, drying, tear-out of ruined material — and expect you to act to prevent further damage, so calling a restoration company immediately is both protection for your home and part of your duty under the policy.
Keep receipts for anything you spend, don't throw away damaged items before they're documented, and open the claim promptly. If you're not sure whether your loss is covered, file anyway and let the carrier decide on facts rather than guesses.
How we work with your claim
Restoration and insurance run on documentation: moisture readings, photo records, itemized scopes and inventories of damaged contents. We produce that record as a normal part of every job — the same readings that guide our drying are the evidence your adjuster reviews. We bill the carrier directly for covered work and help you through the process, including documenting non-salvageable items so nothing you've lost goes unrecorded.
One honest caution: we can't promise what your specific policy will pay — coverage calls belong to your carrier. What we can promise is documentation thorough enough that the decision is made on a complete picture of your loss.
Need This Handled?This guide covers Water Damage Restoration — the service behind this article. Free assessments, 24/7 response across Maryland: (855) 809-6899 or read about the service.
Water Damage Can't Wait — Neither Should You
Every hour of standing water means more damage and a bigger repair. Request your free assessment online and we'll call you back to confirm — or call now and a coordinator will dispatch a crew.